Financing the GBU 57 Cost to Build: 2026 Loan Guide
Discover how to finance the GBU 57 cost to build. Compare construction loans, HELOCs, and cash-out refinances for your 57-foot post-frame garage.
Defining the GBU-57 Garage and Barn Unit
The GBU-57 (Garage & Barn Unit 57) is a highly sought-after 57-foot by 40-foot post-frame building model, yielding 2,280 square feet of versatile workspace. Favored by contractors, hobbyists, and rural property owners, this specific footprint accommodates a 14-foot eave height, allowing for deep vehicle bays, overhead storage, and potential mezzanine additions. However, securing capital for a structure of this magnitude requires navigating a complex landscape of construction lending, material volatility, and appraisal nuances.
Unlike standard stick-built residential additions, post-frame garages rely on embedded columns, engineered trusses, and specialized steel cladding. Understanding the exact financial requirements and matching them with the right lending product is critical to preventing mid-build capital shortfalls.
Quick Cost Snapshot: GBU-57 Turnkey Build
- Base Shell Kit: $38,000 – $46,000
- Site Prep & Concrete: $22,000 – $28,000
- Labor & Erection: $18,000 – $24,000
- Interior Finishing (Insulation/Elec): $15,000 – $22,000
- Total Estimated Range: $93,000 – $120,000
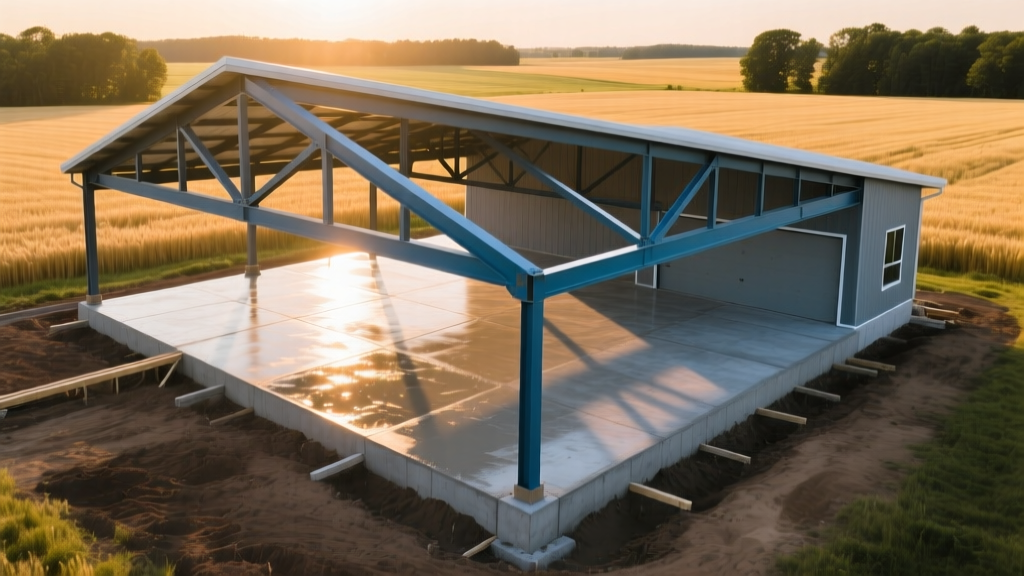
Breaking Down the GBU 57 Cost to Build
To secure accurate financing, lenders require a granular breakdown of your projected expenses. The gbu 57 cost to build is not a single invoice; it is a phased expenditure. Below is a detailed matrix of where your capital will be allocated during a standard 2026 build cycle.
| Construction Phase | Material Specs | Estimated Cost |
|---|---|---|
| Site Preparation | Grading, compaction, vapor barrier | $6,500 - $9,000 |
| Concrete Foundation | 4,000 PSI slab, thickened edges | $16,000 - $19,000 |
| Structural Shell | Laminated columns, 26-gauge steel | $28,000 - $34,000 |
| Roofing System | Engineered trusses, steel panels | $12,000 - $15,000 |
| Insulation & Climate | Closed-cell spray foam (R-21) | $9,000 - $13,000 |
| Electrical & Lighting | 200-amp service, LED high-bays | $6,500 - $9,500 |
Strategic Financing Options for 2026
Funding a 2,280-square-foot outbuilding requires matching your current equity position with the appropriate debt instrument. With construction loan rates stabilizing between 7.25% and 8.5% in early 2026, choosing the wrong financing vehicle can add tens of thousands of dollars in unnecessary interest over the life of the loan.
1. Construction-to-Permanent Loans
This is the most common route for ground-up GBU-57 builds. The lender provides a short-term line of credit to cover the building phase, which automatically converts to a traditional mortgage or property loan once the certificate of occupancy is issued. You only pay interest on the funds drawn during construction. Requirement: Typically requires a 20% down payment and a credit score above 680.
2. Home Equity Lines of Credit (HELOC)
If the GBU-57 is being built on a property where you already hold significant equity, a HELOC offers unparalleled flexibility. You can draw funds exactly when your contractor requires them. In 2026, HELOC rates remain variable, meaning you must budget for potential rate hikes during the 12-to-18-month draw period.
3. USDA Rural Development Loans
For properties located in eligible rural zones, the USDA Single Family Housing programs can sometimes be leveraged to finance essential outbuildings if they are tied to the primary residence's agricultural or functional utility. This is a niche route but offers below-market interest rates for qualifying borrowers.
Comparison Matrix: Choosing Your Loan Product
| Financing Type | Best Use Case | Typical 2026 Rate | Down Payment |
|---|---|---|---|
| Construction-to-Perm | New builds on raw land | 7.5% - 8.5% | 20% Minimum |
| HELOC | Existing property equity | 7.0% - 9.0% (Var) | 0% (Equity based) |
| Cash-Out Refinance | Long-term hold, low LTV | 6.5% - 7.5% | N/A (Refinance) |
| Personal Unsecured | Shell-only, quick funding | 10.0% - 15.0% | 0% |
Navigating the Construction Draw Schedule
Lenders do not disburse the full gbu 57 cost to build upfront. Funds are released in 'draws' tied to specific, verifiable milestones. Mismanaging your draw schedule is the primary reason post-frame builds stall. You must align your builder's payment schedule with your lender's inspection requirements.
- Draw 1: Site Prep & Foundation (15%). Released after soil compaction testing and the pouring of the 4,000 PSI monolithic slab.
- Draw 2: Shell Erection (30%). Disbursed when laminated columns are set, trusses are hoisted, and the structure is plumb and square.
- Draw 3: Dried-In (25%). Triggered once the 26-gauge steel siding, roofing panels, and overhead doors are installed, making the building weather-tight.
- Draw 4: Rough-Ins (15%). Paid upon completion of electrical trenching, interior framing, and spray foam insulation application.
- Draw 5: Final Completion (15%). Released after the final municipal inspection, issuance of the certificate of occupancy, and completion of the punch list.
Hidden Costs and Edge Cases
When calculating your total loan amount, failing to account for soft costs will result in out-of-pocket expenses. According to the National Frame Building Association (NFBA), post-frame construction requires specific engineering documentation that standard residential builds do not.
- Geotechnical Soil Reports ($1,500 - $3,000): Required by many structural engineers to determine the load-bearing capacity of the soil for the embedded columns.
- Wind-Load Engineering Stamps ($800 - $1,200): Essential for permitting, especially in regions prone to high wind shear or heavy snow loads.
- Utility Trenching ($15 - $25 per linear foot): Running dedicated 200-amp electrical service and water lines from the main structure to the GBU-57 site.
Overcoming Post-Frame Appraisal Hurdles
One of the most significant financial roadblocks in financing the GBU-57 is the appraisal process. Many residential appraisers lack experience with modern post-frame construction and may incorrectly value it as a low-tier 'pole barn' rather than a premium, engineered workshop.
To prevent an artificially low appraisal, provide the appraiser with the complete engineered truss drawings, the NFBA certification of your builder, and a detailed list of material upgrades (such as closed-cell spray foam and commercial-grade overhead doors) prior to their site visit.
By treating the GBU-57 as a commercial-grade flex space rather than an agricultural outbuilding, you can ensure the appraised value supports your construction loan amount, preventing the need for unexpected cash injections.
Frequently Asked Questions
Can I use an FHA 203(k) loan to build a detached GBU-57 garage?
No. The FHA 203(k) rehabilitation loan program is strictly limited to the primary residence and attached structures. Detached outbuildings like the GBU-57 must be financed through conventional construction loans, HELOCs, or specialized rural development programs.
How does the choice of steel gauge affect my financing?
Upgrading from standard 29-gauge to 24-gauge or 26-gauge steel panels increases the upfront material cost by roughly 15% to 22%, but it significantly boosts the building's longevity and insurability. Lenders prefer thicker gauge steel as it protects their collateral against severe weather damage.
What happens if material costs spike during the build?
Most construction loans include a 'contingency reserve' of 10% to 15%. If the cost of engineered lumber or steel coils spikes mid-build, these reserve funds are drawn upon. If the contingency is exhausted, the borrower must cover the overage out-of-pocket.
Written by
Priya KapoorPriya Kapoor is a real estate market analyst and construction economics researcher with expertise in housing affordability, development feasibility, and infrastructure investment. She holds a Master of Regional Planning from Cornell University and previously worked as a senior analyst at CBRE's Investment Properties group, where she modeled returns for $4B in mixed-use development pipelines. Priya now runs an independent research practice advising developers, municipalities, and REITs on construction cost forecasting and market timing. She publishes the quarterly "BuildMat Market Pulse" report tracking material price indices across 12 commodity categories. Based in Austin, TX, Priya serves on the board of Habitat for Humanity Austin and is a marathon runner.
More from Priya Kapoor
View all
Construction Cost
Cost to Build a 1600 Sq Ft Home in 2026: Full Breakdown
Accurate 2026 cost to build a 1600 sq ft home—material, labor, and regional pricing breakdowns included. Plan your budget with real-time estimates.
Aug 11, 2026

Wood & Lumber
Name the Types of Wood for Pressure Treatment and Preservation
Learn how to name the types of wood best suited for pressure treatment. Compare species treatability, chemical retention levels, and 2026 preservation costs.
Aug 4, 2026

Stone & Masonry
Stone Veneer Suppliers Lindenhurst: 2026 Cost Analysis
Analyze 2026 stone veneer costs in Lindenhurst, NY. Compare local supplier pricing, delivery fees, and Suffolk County installation labor rates.
Aug 4, 2026